Our Articles
Latest Home Loan Posts
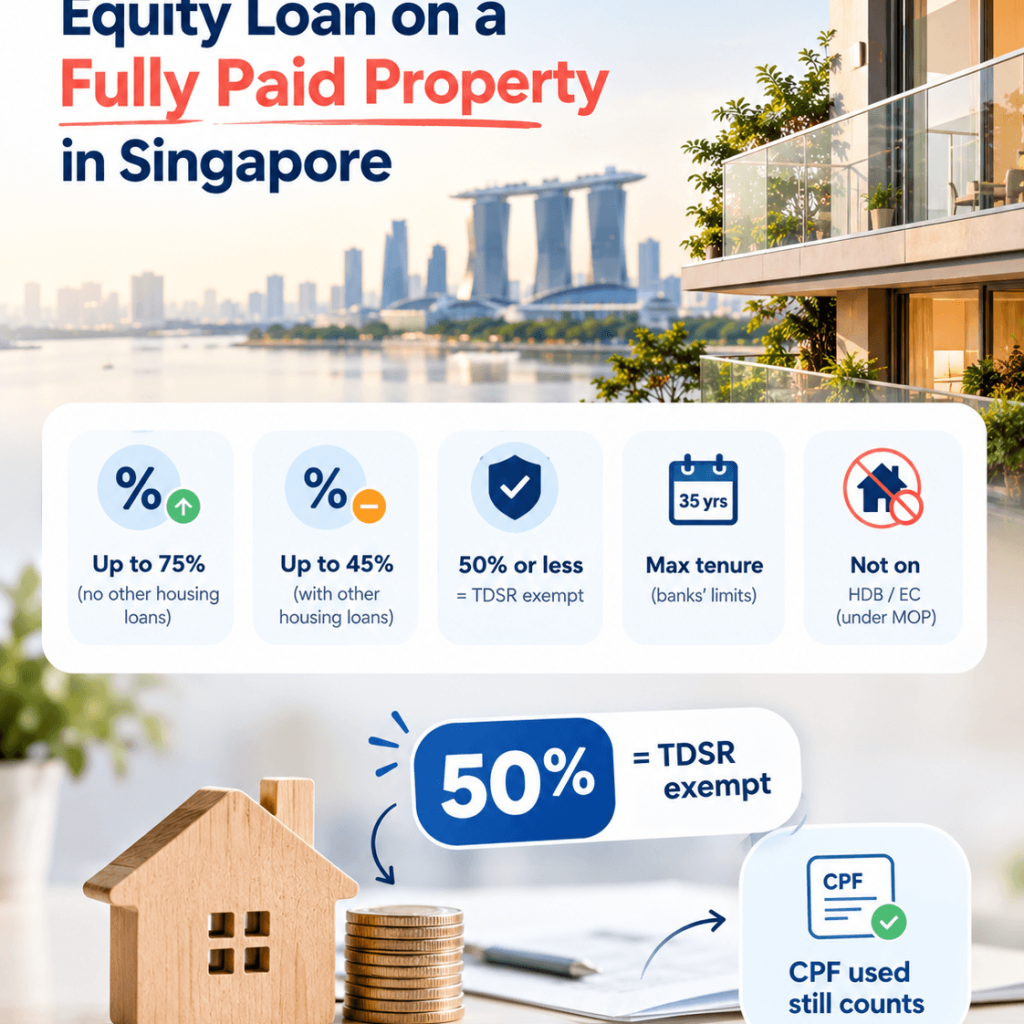
Equity Loan on a Fully Paid Property in Singapore
Can You Take an Equity Loan on a Fully Paid Property? Quick answer Yes, if it’s private property. With no other housing loans, the applicable cap is 75% of its current valuation, less CPF monies used to buy it. For an initial estimate, include both CPF principal withdrawn and accrued interest. If you have another
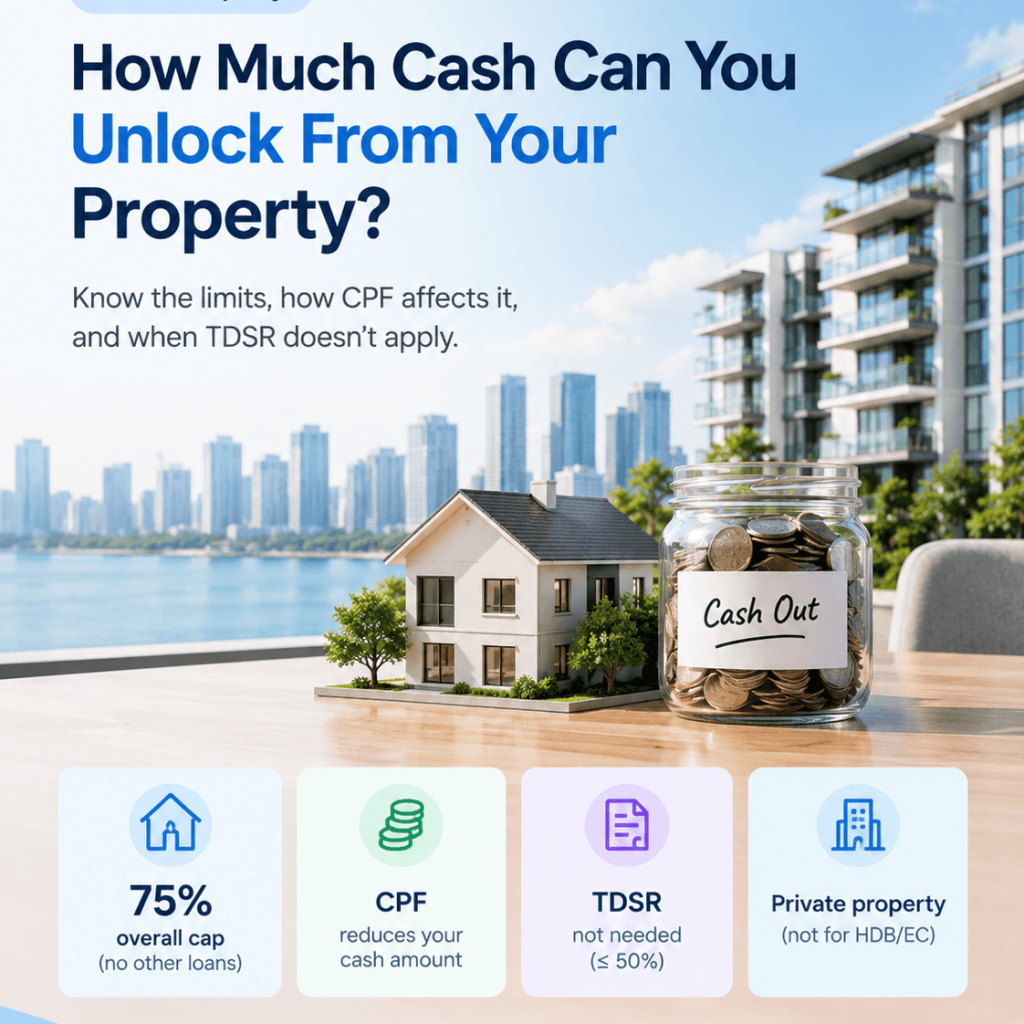
How Much Cash Can You Unlock From Your Property?
How Much Cash Can You Unlock From a Private Property? Quick answer With no other housing loans, the overall cap on borrowing against your private property is 75% of its current valuation. The maximum new equity loan is the remaining headroom after subtracting your outstanding mortgage and CPF used for the property. For an initial
How Much Can I Borrow for a Property in Singapore?
How Much Can I Borrow for a Property in Singapore? Quick answer You can borrow the lower of two amounts. The first is the loan-to-value (LTV) limit: up to 75% of the price or valuation, whichever is lower, if you have no other housing loan. The second is the loan your income can carry: total
IPA Lower Than Expected? How to Close the Gap
What Can You Do If Your In-Principle Approval Is Lower Than Expected? Quick answer An in-principle approval (IPA) can come in lower than expected because of a shorter loan tenure, income the bank counts at less than face value, or a valuation below the price. An IPA is not a final loan offer. Work out
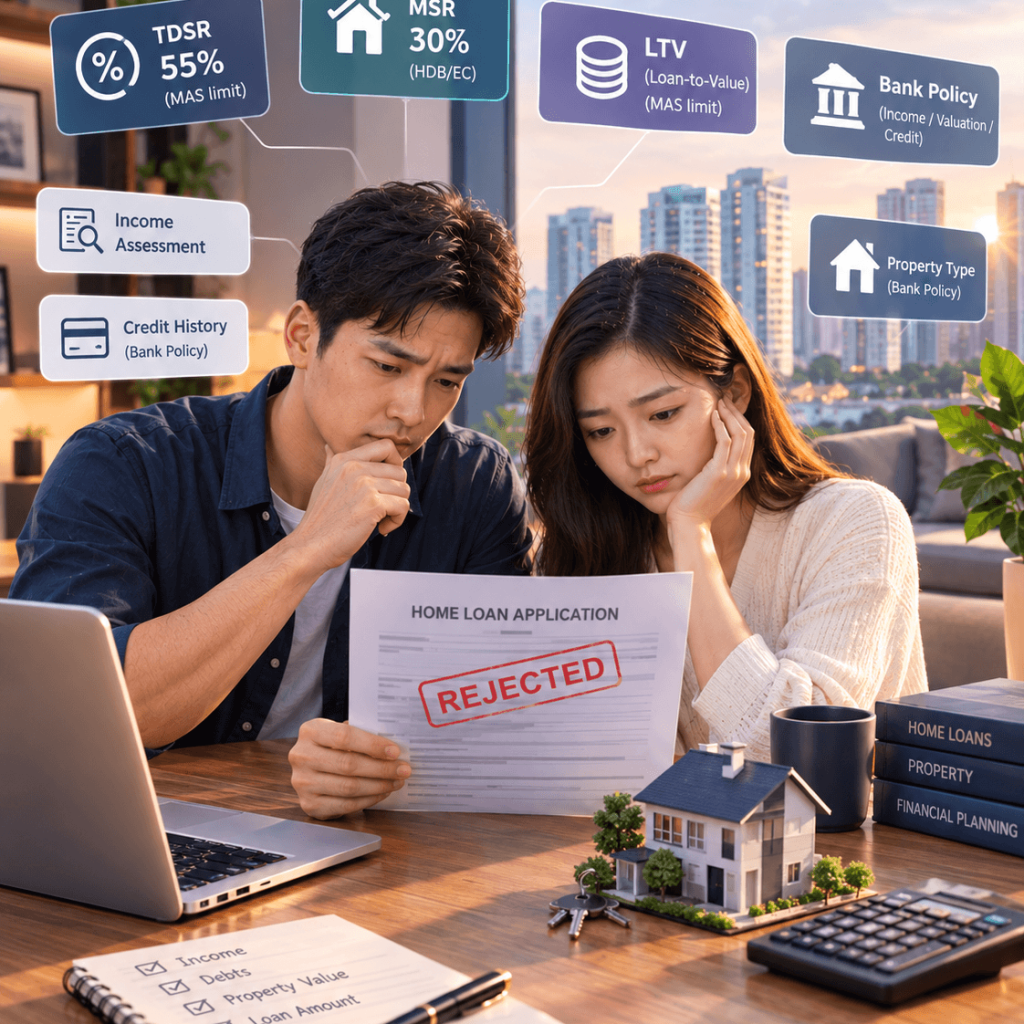
Home Loan Rejected in Singapore? What to Do Next
Home Loan Options After a Bank Rejects Your Application Quick answer A rejected home loan usually comes down to one of two things: a national limit you didn’t meet, or one bank’s own credit policy. The limits — the 55% Total Debt Servicing Ratio (TDSR), the 30% Mortgage Servicing Ratio (MSR) for HDB flats and
Fixed Rate vs SORA Home Loan in Singapore: Which Should You Choose?
Quick answer A fixed-rate mortgage locks your rate for a stated period; a SORA-linked mortgage moves with compounded SORA plus the bank’s spread. Today the lowest 2-year fixed rate is 1.40%* and the cheapest SORA package is 3-month SORA + 0.20% = 1.4169%*. That puts the break-even at a 3-month SORA of 1.20%: above it,
Can You Refinance a Home Loan During the Lock-In Period in Singapore?
Quick answer Yes, you can refinance a Singapore bank home loan during its lock-in period, but you will pay an early redemption penalty – 1.50% of the amount redeemed on the packages we track – plus any subsidy clawback. On a $1.5M loan that is $22,500 before clawbacks. Switching early pays off only when the
Repricing vs Refinancing in Singapore: Which Could Save You More?
Quick answer Repricing means switching to a new package with your existing bank; refinancing means moving your mortgage to another bank. Repricing costs $500-$800, with no legal or valuation fees and no clawback. Refinancing opens up the whole market but brings legal and valuation costs and a 3-year subsidy clawback. Once your lock-in ends, either

Useful Credit Cards for New Families
Settling down, getting married and starting a new family are part of the wonderful journey of life. For couples in Singapore though, these checkpoints also represent some of the most financially-challenging moments in life – because despite what Hollywood believes, most of us aren’t actually Crazy Rich Asians. Crazy expenses, not-so-rich Asians Expenses are going