Home Loan Rejected in Singapore? What to Do Next
Home Loan Options After a Bank Rejects Your Application
Quick answer
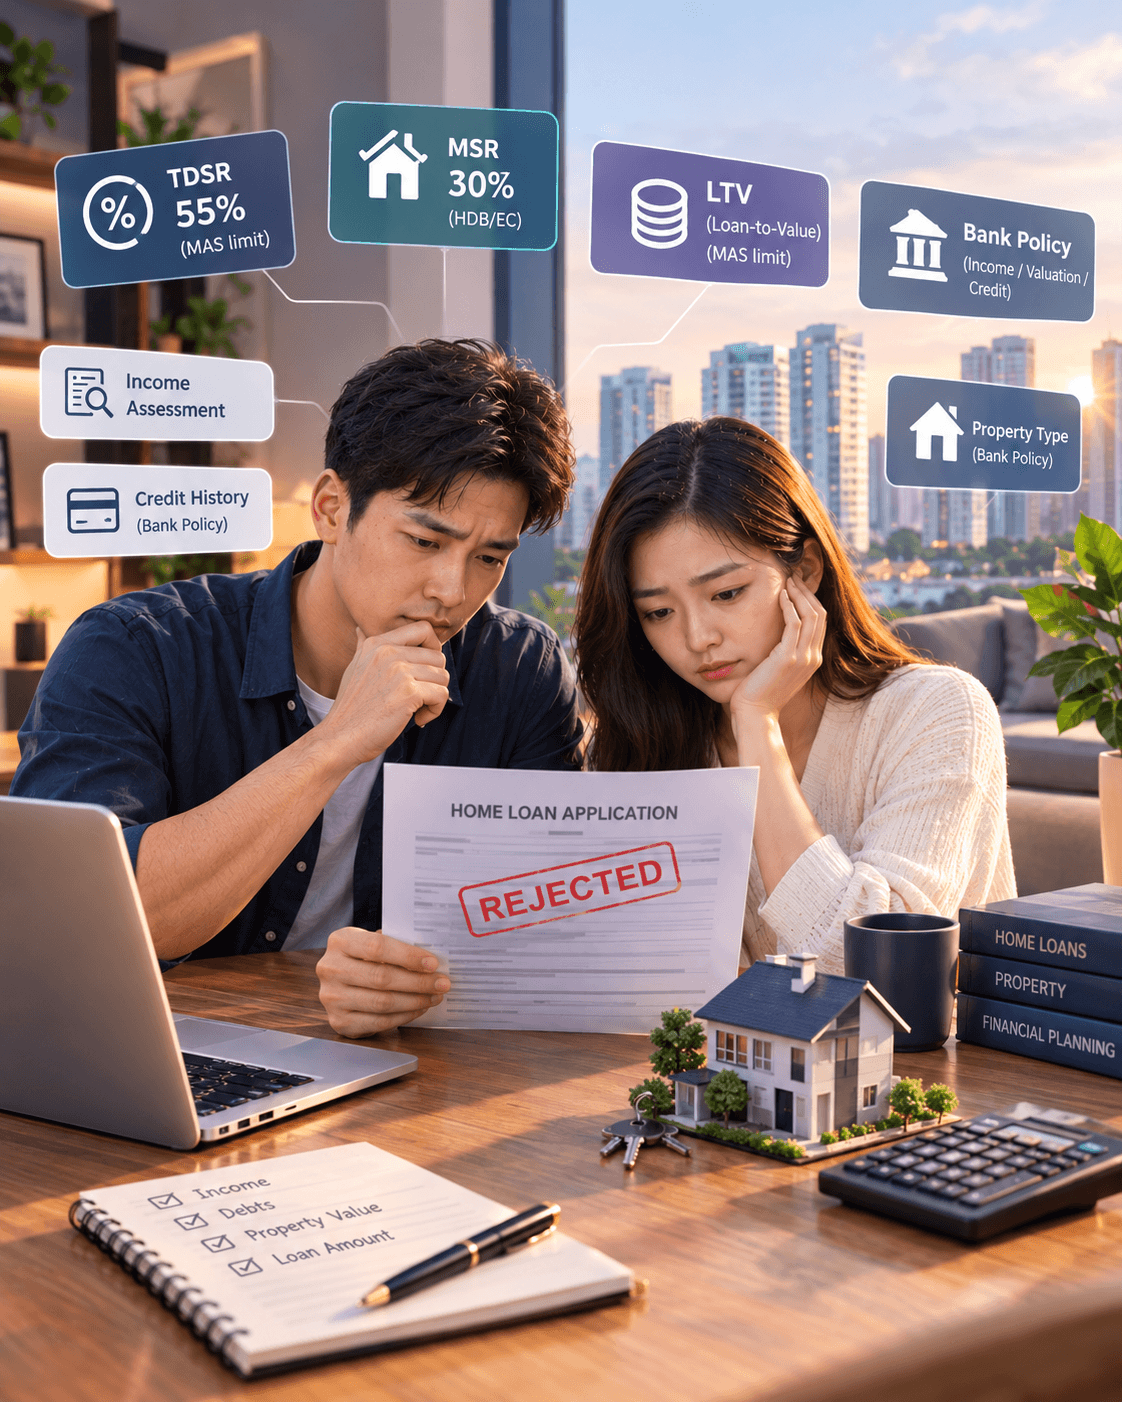
A rejected home loan usually comes down to one of two things: a national limit you didn’t meet, or one bank’s own credit policy. The limits — the 55% Total Debt Servicing Ratio (TDSR), the 30% Mortgage Servicing Ratio (MSR) for HDB flats and ECs, and loan-to-value limits — are the same at every bank. But each bank applies them to its own assessment of your income, debts and the property’s value, so results can differ. Find out what stopped you before you apply again.
The question that matters
Was your application stopped by a limit every bank must follow, or by this bank’s own credit policy or assessment? If you are well over a national limit, changing the numbers is the reliable fix. If it’s bank policy — or a borderline result that depends on how your income or property was assessed — a different lender may reach a different answer.
Why banks reject home loans — and which reasons another bank can’t fix
| Reason | Limit set by MAS, or bank policy? | What to check | What can change it |
|---|---|---|---|
| Total debt above 55% of income (TDSR) | MAS limit; the income and debts counted are each bank’s assessment | Your recognised income and all monthly debt repayments | Pay down other debts, pledge or show financial assets, add a co-borrower, borrow less |
| HDB or EC loan instalment above 30% of income (MSR) | MAS limit; income counted is the lender’s assessment | Gross monthly income of all buyers | Add a buyer with income, borrow less, choose a lower price |
| Loan amount above the LTV limit | MAS limit | Number of existing housing loans, tenure, age at end of loan | Larger downpayment, shorter tenure |
| Valuation below purchase price | MAS limit applies to the lower figure; each bank obtains its own valuation | The bank’s valuation against your price | Cash top-up, or another bank’s valuation |
| Variable or self-employed income recognised below what you expected | MAS requires a minimum 30% haircut on variable income. Separately, HLW commonly uses a 30% haircut on self-employed assessed income for an initial estimate; lenders decide the actual amount recognised | Which income the bank counted, and how | Fuller income records, or a bank with different documentation requirements |
| Credit history | Bank policy | Your Credit Bureau Singapore report | Correct any errors; address outstanding arrears first |
| Property type or remaining lease | Bank policy | The bank’s stated reason | A lender with a different policy on that property |
If the bank hasn’t told you which reason applied, ask. You need the answer before choosing what to do next.
How the national rules work
TDSR. Your total monthly debt repayments — the new mortgage plus car loans, personal loans and other credit — must stay at or below 55% of your gross monthly income. The bank doesn’t use your actual mortgage rate for this test. For residential property, it uses the higher of 4% or the package’s later (“thereafter”) rate. Whenever that later rate is below 4%, the test runs at 4%.
Income haircuts. MAS requires banks to discount bonuses, commission, allowances and rental income by at least 30%. For self-employed assessed income, HLW also commonly starts its indicative calculation with a 30% haircut. That is an HLW working assumption, not a guarantee of how a particular bank will assess an application.
Financial assets. Savings and investments can be converted into deemed monthly income, spread over 48 months:
- Cash pledged with the bank for at least 4 years: no minimum haircut.
- Cash shown but not pledged: a minimum 70% haircut.
- Other assets, such as shares or unit trusts: a minimum 30% haircut if pledged for at least 4 years, and 70% if not.
- Unpledged assets must be separate from the money you’re using for the downpayment.
MSR. For an HDB flat or EC, the monthly property loan instalment must not exceed 30% of gross monthly income. This applies on top of TDSR.
LTV. With no outstanding housing loan, a bank can lend up to 75% of the price or valuation, whichever is lower. The limit falls to 55% if the tenure exceeds 30 years (25 for an HDB flat) or the loan runs past age 65. With one outstanding housing loan, the limit is 45%. HDB’s own loans are capped at 75% (lowered from 80% on 20 August 2024).
Illustration: how each fix changes a TDSR rejection
Illustration — not a client case. A 35-year-old buyer is purchasing a $1,500,000 private condo and needs a $1,125,000 loan (75% LTV) over 30 years. They have the $375,000 downpayment ready (25%, of which at least 5% must be cash), plus stamp duty and fees. Their income is $8,000 a month fixed plus $2,000 a month in average bonus. They have a car loan of $1,100 a month. The bank in this example applies the MAS minimum haircuts — another bank may apply larger ones.
- Recognised income: $8,000 + ($2,000 × 70%) = $9,400.
- TDSR limit: 55% × $9,400 = $5,170 a month for all debt.
- At the 4% stress rate, a $1,125,000 loan over 30 years tests at $5,371 a month. Adding the car loan puts TDSR at 68.8%, so the application fails.
Any savings shown or pledged below are additional to the $375,000 downpayment and the stamp duty money — the same funds cannot be counted twice.
| Change | Income counted | Room for the mortgage | Largest loan that passes TDSR at 4%, 30 years |
|---|---|---|---|
| As applied | $9,400 | $4,070 | about $852,500 |
| Clear the car loan | $9,400 | $5,170 | about $1,082,900 |
| Show a further $200,000 cash, not pledged | $10,650 | $4,758 | about $996,500 |
| Pledge a further $200,000 cash for 4+ years | $13,567 | $6,362 | about $1,332,500 |
Clearing the car loan alone comes up about $42,000 short. Clearing it and pledging around $17,500 of extra cash — on top of the downpayment — for four years closes the gap.
Another bank uses the same 55% limit and 4% floor, but its result can still differ if it recognises the bonus differently, applies a larger haircut, or values the property differently. Switching banks helps only to the extent those assessments differ. Changing the inputs — debts, assets pledged, borrowers, loan size — moves the result at any bank.
What to do next
- Get the reason. Ask the bank which rule or policy stopped the application. Note the figures they used: recognised income, valuation, loan amount.
- Sort it into national rule or bank policy, using the table above.
- If you’re over a national limit, rework the numbers before applying anywhere: clear or reduce other debts, pledge or show assets (separate from your downpayment), add a co-borrower, extend or shorten the tenure within the limits, or borrow less.
- If it’s bank policy, or a borderline assessment, compare lenders whose approach differs on that point — valuation, how they recognise your income, documents or property type.
- Check your credit report with Credit Bureau Singapore before you reapply, so there are no surprises.
- For an HDB flat, check whether an HDB loan is an option. Your HDB Flat Eligibility (HFE) letter shows whether you qualify and how much you can borrow.
If your loan was approved, but for less than you need, see our guide on an in-principle approval lower than expected. Ask an adviser to calculate your borrowing capacity before committing to a purchase.
Frequently asked questions
Is the TDSR limit different at each bank?
The limit isn’t. The 55% cap and the 4% stress rate are MAS rules for every bank. What can differ is the input: how much of your income a bank recognises (MAS sets minimum haircuts, not maximums), how it values the property, and its own credit policy. So the same application can produce different results at different banks.
Does the 4% stress rate mean I’ll pay 4% interest?
No. It’s only used to test affordability. You pay the package rate you’re offered.
Can a co-borrower help?
Often, yes. Their income is added to the assessment, but so are their own debts, and their age affects the maximum tenure and LTV.
Can the cash for my downpayment also count towards TDSR?
No. Unpledged assets used for TDSR must be separate from your downpayment funds.
If I’m buying an HDB flat, which limit applies — MSR or TDSR?
Both. The instalment must stay within 30% of income for MSR, and your total debts within 55% for TDSR.
Rejected? Find out why before you reapply
Send us what the bank told you (or the rejection letter), the property price and type, your gross monthly income split into fixed and variable, your existing monthly debt repayments, and the age of each borrower. We’ll work out which rule or policy stopped the application and what would change the outcome.
Check Why My Loan Was Rejected. Destination to be added during publishing.
Related guides
Sources: MAS — Calculating TDSR for Property Loans; MAS — Loan Tenure and Loan-to-Value Limits; MAS — Rules for New Housing Loans; MoneySense — Buying a property: how much can you afford?; ABS — About Home Loans; HDB — Measures to cool the HDB resale market; Credit Bureau (Singapore). Rules as at 10 October 2026