Equity Loan on a Fully Paid Property in Singapore
Can You Take an Equity Loan on a Fully Paid Property?
Quick answer
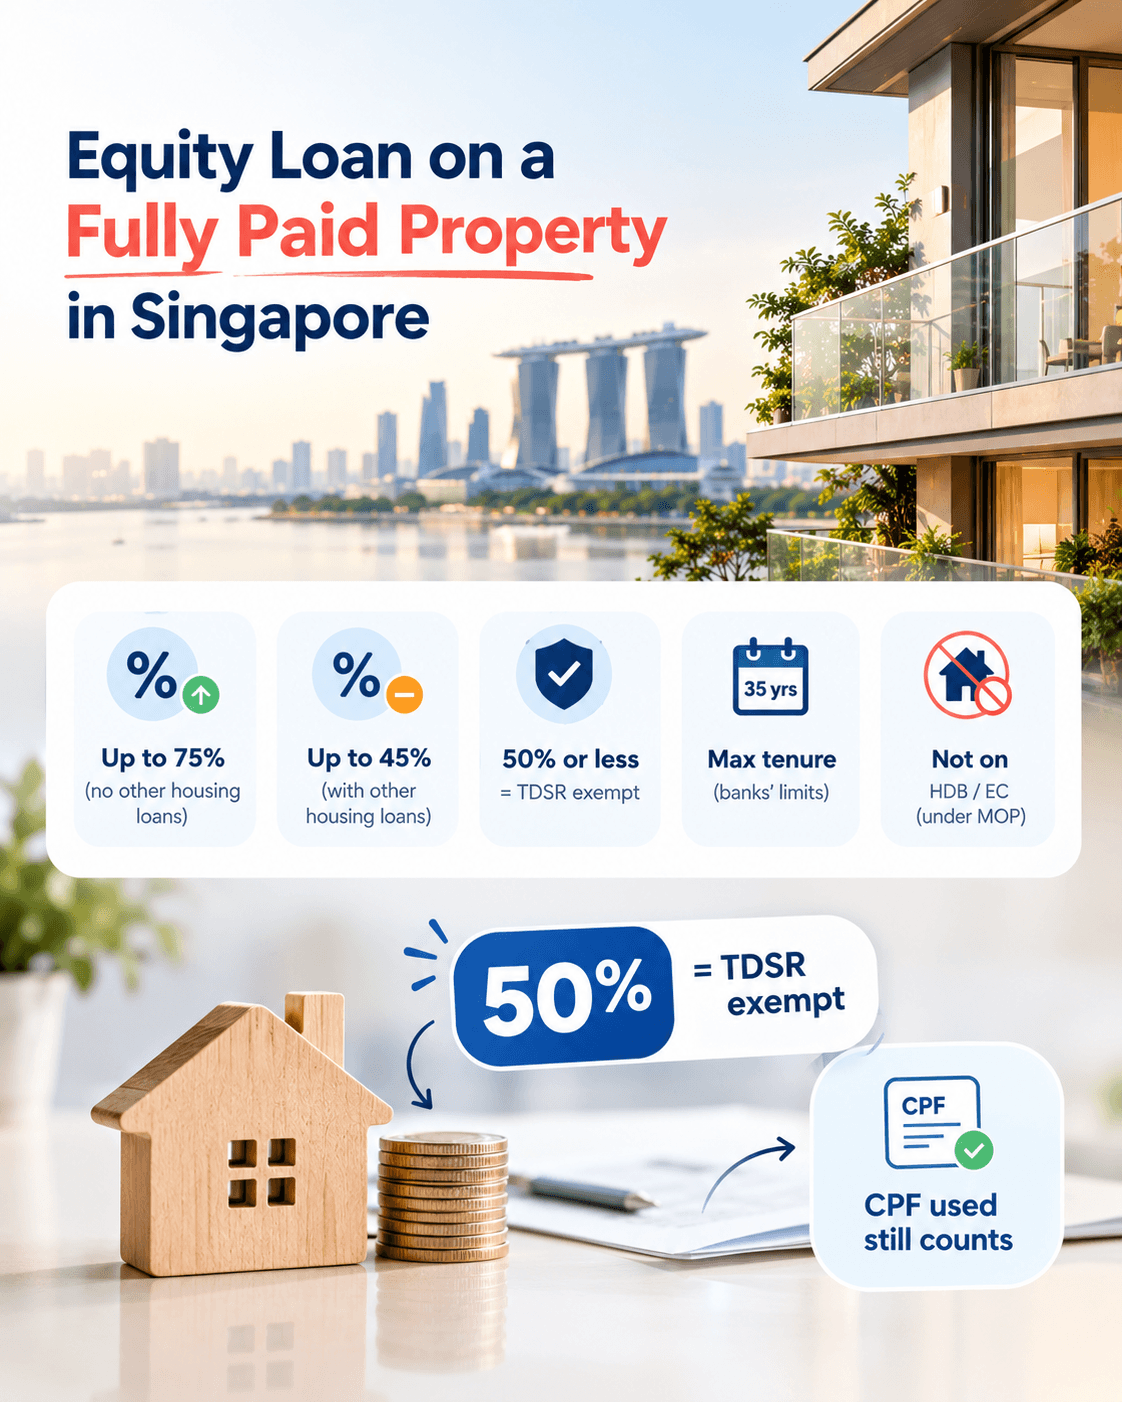
Yes, if it’s private property. With no other housing loans, the applicable cap is 75% of its current valuation, less CPF monies used to buy it. For an initial estimate, include both CPF principal withdrawn and accrued interest. If you have another housing loan, the cap is 45%. At 50% of valuation or less, the loan is exempt from the TDSR calculation, but the bank still assesses your ability to repay. Equity loans can’t be taken on HDB flats, or on ECs still within their minimum occupation period.
The question that matters
Do you need more than half your property’s value? Up to 50%, MAS exempts the loan from TDSR. The bank still decides what you can borrow after assessing your ability to repay.
Fully paid property: the numbers that apply
| Rule | Limit |
|---|---|
| Cap, no other housing loans | 75% of current valuation, less CPF monies used; HLW’s initial estimate includes principal and accrued interest |
| Cap, one or more other housing loans | 45% of current valuation, less CPF monies used; lender assessment determines the actual limit |
| TDSR | Not applied if the loan is 50% or less of current valuation |
| Maximum tenure | 35 years (banks also set their own age limits) |
| Not available on | HDB flats; ECs within their minimum occupation period |
Why a fully paid home is different
With no mortgage on the property, the CPF you used to buy it still counts towards the cap. That makes the 50% line a key planning point. MAS set it partly so owners can draw on their property in retirement without needing to pass the TDSR calculation. The bank still performs a credit assessment.
Home Loan Whiz | Final approval requested
Above 50%, the loan goes through TDSR: your total debts must fit within 55% of income, tested at a 4% rate. If your income can’t support that test, the 50% line effectively sets the size of your loan.
Worked example: $1.8M fully paid condo
Illustration — not a client case. A homeowner owns a condo valued at $1,800,000 with no mortgage. They withdrew $250,000 of CPF principal to buy it years ago and have an assumed $50,000 of accrued interest. They have no other housing loans. The actual accrued interest must be checked against the CPF statement.
| Step | Amount |
|---|---|
| 75% × $1,800,000 | $1,350,000 |
| Less CPF principal and assumed accrued interest | –$300,000 |
| Illustrative maximum equity loan | $1,050,000 |
| Borrowable with no TDSR check: 50% × $1,800,000 | $900,000 |
Up to $900,000 falls within the TDSR exemption, subject to the bank’s credit assessment. Going above that, up to the illustrative $1,050,000 cap, means passing TDSR; the portion above the no-TDSR line is $150,000. With another housing loan elsewhere, the illustrative cap drops to 45%: $810,000 less the $300,000 CPF amount leaves $510,000. The final amount depends on the lender’s assessment.
Before you apply
- Get a current valuation. The cap moves with the market.
- Find your CPF principal and accrued interest on your CPF statement.
- Decide whether 50% is enough. Staying at or under it avoids the TDSR calculation, although the bank still assesses repayment ability.
- Check the tenure. It’s capped at 35 years, and the bank’s own age limit may shorten it.
- Plan the repayment. The loan is secured on a home you own outright, so missed repayments put that home at risk.
Frequently asked questions
Do I need an income to qualify?
You do not need to pass the TDSR calculation if the loans secured on this property total 50% or less of its valuation. The bank still assesses your ability to repay and may require income information.
Can I take an equity loan on my fully paid HDB flat?
No. MAS doesn’t allow these loans on HDB flats.
Is the CPF I used still deducted if the property is fully paid?
Yes. MAS counts CPF monies used inside the LTV cap, whether or not the property has a mortgage. HLW includes principal withdrawn plus accrued interest in its initial estimate; the bank confirms the amount it uses.
Can I repay the loan with CPF?
Ask the bank. At least one bank states that CPF can’t be used for its property equity loan.
Home Loan Whiz | Final approval requested
Find out what your property can support
Send us the property type and estimated value, the CPF principal and accrued interest for the property, any other housing loans, your age, and any income. We’ll estimate the cap and whether you can stay under the TDSR line.
Related guides
Sources: MAS — Mortgage Equity Withdrawal Loan Rules; MAS — Written reply on mortgage equity withdrawal loans, 14 January 2026; DBS — Cash-Out Loan; UOB — Managing your property loan. Rules as at 10 October 2026.