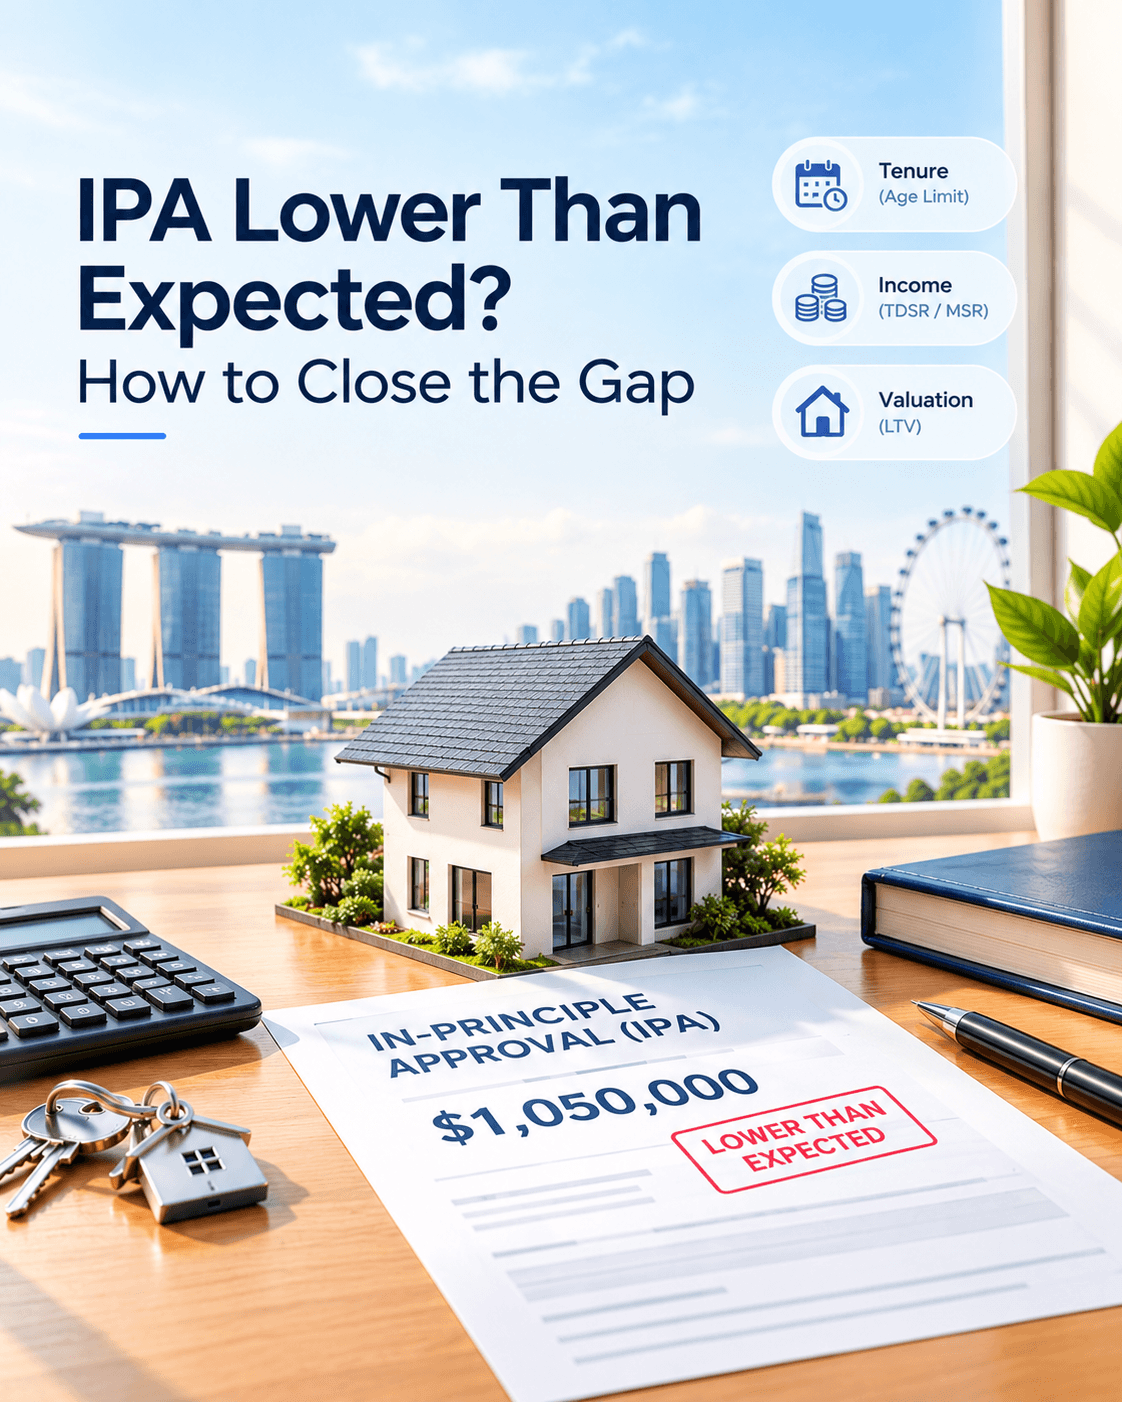
IPA Lower Than Expected? How to Close the Gap
What Can You Do If Your In-Principle Approval Is Lower Than Expected?
Quick answer
An in-principle approval (IPA) can come in lower than expected because of a shorter loan tenure, income the bank counts at less than face value, or a valuation below the price. An IPA is not a final loan offer. Work out which limit reduced the amount before exercising an Option to Purchase (OTP), and check the financing and legal deadlines if your exercise date is close.
The question that matters
Which limit set your IPA amount — your income (TDSR or MSR) or the property’s value (LTV)? The fixes are different. More recognised income won’t help if the valuation is the limit, and a better valuation won’t help if your income is.
What usually lowers an IPA
| Cause | How it cuts the amount | What can close the gap |
|---|---|---|
| Tenure shortened by age | To keep the 75% LTV, the loan can’t run past age 65 or exceed 30 years (25 for an HDB flat). A shorter tenure raises the stress-test instalment, which lowers the loan TDSR allows | A younger co-borrower (age is income-weighted), a smaller loan, or accepting the lower LTV for a longer tenure |
| Variable income counted at a discount | Bonuses, commission and allowances are averaged over 12 months and counted at no more than 70% | Pledge or show financial assets, add a co-borrower, reduce other debts |
| Self-employed income recognised below your estimate | HLW commonly applies a 30% haircut to assessed income for an initial estimate; the lender decides the actual recognised amount and documents needed | Check the lender’s assessment, prepare the requested Notices of Assessment and supporting records, or compare lenders |
| Valuation below price | LTV applies to the price or valuation, whichever is lower | Pay the shortfall in cash or CPF, or ask another bank for its valuation |
| Other monthly debts | Car, personal and other loans count towards the 55% TDSR | Repay or reduce them before the formal application |
| HDB flat or EC | The instalment must also fit within 30% of income (MSR) | Add income, borrow less, or check HDB loan eligibility through your HFE letter |
How the limits combine
The bank works out two numbers and offers the lower one:
- LTV limit: up to 75% of the price or valuation, whichever is lower, if you have no other housing loan.
- Income limit: the loan whose instalment, tested at 4% interest, keeps all your debts within 55% of recognised income (TDSR). For HDB flats and ECs, it must also stay within 30% for property loans (MSR).
For joint borrowers, tenure is based on the income-weighted average age of the borrowers.
Illustration: how a $1.2M expectation became about $1.05M
Illustration — not a client case. A 40-year-old buyer is purchasing a $1,600,000 condo and expects a $1,200,000 loan (75%) over 30 years. They earn $8,000 a month fixed plus $3,000 a month in average bonus, and have no other debts. The bank applies the MAS minimum haircut.
| Step | Effect | Largest loan |
|---|---|---|
| Buyer’s assumption: $11,000 income, 30 years | 75% of price | $1,200,000 |
| Tenure capped at 25 years (age 40 to 65) | TDSR at 4% on $11,000 | about $1,146,200 |
| Bonus counted at 70% → $10,100 income | TDSR at 4%, 25 years | about $1,052,400 |
| Bank values the property at $1,550,000 | 75% of valuation | $1,162,500 |
| IPA | Lower of income limit and LTV limit | about $1,052,400 |
The gap to $1,200,000 is about $147,600. Here, income is the binding limit.
- Pledging a further $100,000 of cash for four years — separate from the downpayment — adds about $2,083 a month of recognised income, which lifts the TDSR limit to about $1,269,500. The loan is then capped by the valuation at $1,162,500.
- Adding a 32-year-old spouse earning $5,000 fixed brings the income-weighted average age to about 37, which allows a 27-year tenure and lifts the TDSR limit well above the LTV cap. Again, the loan stops at $1,162,500.
- Either way, the valuation remains. At $1,162,500, the buyer needs $437,500 in cash and CPF, of which at least 5% of the price must be cash, instead of $400,000. The extra $37,500 has to be found unless another bank values the property higher.
What to do before your OTP expires
- Ask the bank how it reached the figure: tenure, recognised income and valuation.
- Identify which limit binds — income or valuation.
- If it’s income: consider a co-borrower, pledging or showing assets (separate from the downpayment), or reducing other debts.
- If it’s valuation: budget for the shortfall, or compare valuations from other banks.
- Check timing. An IPA is “typically valid for 30 days” (ABS), but each bank sets its own validity. Confirm the date on yours, plus the financing and legal deadlines under your OTP, before exercising it.
Frequently asked questions
Is an IPA a guaranteed loan offer?
No. ABS describes it as “not a binding document”. It’s typically based on what you declared, and the formal application may still change the amount.
Will a longer tenure fix a low IPA?
Only up to a point. Going beyond 30 years (25 for HDB flats), or past age 65, drops the LTV limit from 75% to 55%.
Does adding a co-borrower always help?
Not always. Their income helps, but their debts also count, and their age changes the weighted average used for tenure.
My IPA is for an HDB flat. Can an HDB loan give more?
Possibly. HDB assesses its own loan using a 3% interest-rate floor and its own criteria. Your HFE letter, valid for 9 months, shows whether you’re eligible and how much.
Short on your IPA? Send us the numbers
Send us your IPA amount and bank, the purchase price, your OTP exercise date, the age and income (fixed and variable) of each borrower, and any existing monthly debts. We’ll identify which limit set the amount and what would close the gap.
Related guides
Sources: ABS — About Home Loans; MAS — Loan Tenure and LTV Limits; MAS — Calculating TDSR; MAS — 2022 property measures; MoneySense — How home loans work; HDB — HFE letter validity. Rules as at 10 October 2026.